Law
What Happens to Your Retirement Contributions While Receiving L&I Benefits?

When a workplace injury occurs in Washington, the immediate focus is understandably on recovery and the “time-loss” payments that replace a portion of missing wages. However, as weeks turn into months, many workers notice a secondary financial shift: the quiet stalling of their retirement savings. Because of the way the Department of Labor and Industries (L&I) classifies benefits, the impact on 401(k) plans, IRAs, and pension contributions is often more significant than claimants realize.
The Nature of L&I Benefits vs. Earned Income
The core of the issue lies in the legal definition of the money you receive. In the eyes of the IRS and most retirement plan administrators, L&I time-loss payments are considered disability benefits, not “earned income” or “wages.”
Most employer-sponsored retirement plans, such as a 401(k) or a 403(b), are funded through payroll deductions. Since you are not receiving a standard paycheck from your employer while on total temporary disability, those automatic deductions stop. Furthermore, because time-loss isn’t earned income, you generally cannot contribute to a Traditional or Roth IRA using those funds. This results in a “contribution gap” that can significantly alter the long-term growth of a retirement nest egg.
Employer Matching and Pension Credits
For many Washington workers, the real loss isn’t just their own contribution, but the employer’s “free money.”
The Loss of the Employer Match
Most companies only provide a matching contribution if the employee is actively contributing from their salary. When you move from a payroll check to an L&I check, the match typically vanishes. For a worker out of commission for a year or more, this lost compound interest can represent thousands of dollars in forfeited future wealth.
Impact on Defined Benefit Pensions
Workers in unions or government positions often rely on “years of service” or “hours worked” to calculate their future pension. Depending on the specific language of the collective bargaining agreement or the pension plan’s bylaws, time spent on L&I may not count toward these service credits. While some generous contracts allow for “imputed” hours during disability, many do not, potentially pushing back a worker’s retirement eligibility date.
Navigating the Financial Friction
This disruption often creates a sense of financial vertigo. You are dealing with the physical pain of an injury while watching your financial future stagnate. This complexity is why many people choose to consult with a legal professional to ensure they are maximizing every aspect of their claim. If you find yourself overwhelmed by how your injury is affecting your broader financial health, you can click here to learn more about the nuances of the Washington workers’ compensation system.
Practical Considerations for Long-Term Claims
If you anticipate being on L&I for an extended period, there are a few factors to keep in mind:
- Social Security Credits: Because time-loss payments are not subject to Social Security taxes, you are not earning Social Security “credits” during this period. This could slightly lower your future Social Security retirement benefit.
- The “Catch-Up” Strategy: Once you return to work, you may need to increase your contribution percentage to compensate for the time lost.
- Tax Implications: While L&I benefits are generally tax-free at the federal level, the lack of taxable income means you lose the tax deduction benefit usually associated with 401(k) contributions.
Common Questions Regarding Retirement and L&I
Can I use my L&I check to fund my IRA?
Generally, no. To contribute to an IRA, you must have “taxable compensation.” Since L&I benefits are tax-exempt disability payments, they do not qualify as the basis for an IRA contribution.
Does my employer have to keep contributing to my retirement while I’m hurt?
Unless you have a specific employment contract or union agreement that states otherwise, most employers are not legally required to continue retirement contributions or matching while you are not performing work.
What happens to my 401(k) loan?
This is a major risk. If you have an outstanding loan against your 401(k) and your payroll deductions stop, the loan could go into default, triggering taxes and penalties. You may need to arrange manual payments with your plan provider to avoid this.
Summary
The Washington L&I system is designed to keep you afloat during a crisis, but it isn’t perfectly calibrated to protect your long-term investment goals. Understanding that your retirement accounts will likely “freeze” during your recovery allows you to plan more effectively for your return to the workforce. While the immediate goal is always physical healing, staying mindful of the paper trail and the contribution gap is essential for a full financial recovery.
You May Also Read: Decreto Supremo 160 Explained: Key Requirements, Compliance Guide, and Practical Insights

For Wilmington business owners, a personal guarantee can turn a company obligation into a household financial concern. Whether the business operates near the Port of Wilmington, serves the coastal tourism market, or provides professional services across New Hanover County, a lender, landlord, supplier, or equipment lessor may request one. An asset protection lawyer evaluates the guarantee within the broader context of personal property, business operations, insurance, existing debt, and family goals.
A personal guarantee does not automatically mean a business owner will lose personal assets. It does mean the signer may have a separate contractual obligation if the business does not perform as promised. Careful review before signing, and early planning when a problem appears, can help identify exposure and preserve lawful options.
How Asset Protection Lawyers Assess the Risks of Personal Guarantees
Why Personal Guarantees Require Close Attention
Businesses often need credit before they have a long operating history or substantial assets. A creditor may therefore ask an owner, member, shareholder, or spouse to guarantee payment. The company remains responsible for the underlying obligation, but the guarantor may also be responsible under a separate agreement.
In North Carolina, an agreement to answer for another person’s debt generally must be in writing and signed by the party being charged. This state requirement is one reason the signed documents, amendments, and related loan papers matter so much during a review.
How Lawyers Identify the Real Exposure
Start With the Entire Financial Picture
An assessment begins with an inventory, not just the guarantee itself. A lawyer may ask what the individual owns, how each asset is titled, whether it is jointly owned, and whether it is already pledged as collateral. The review can include a primary residence, rental property, bank accounts, investments, retirement assets, vehicles, business interests, valuable equipment, and expected inheritances.
The goal is not to hide property or avoid legitimate obligations. Instead, the goal is to understand what could be vulnerable, what may have legal protections, and where practical changes may be available before a dispute or default occurs.
Read the Guarantee, Not Just the Loan Summary
Personal guarantees vary widely. Some apply only to one identified loan, lease, or purchase agreement. Others are continuing guarantees that may cover future advances, renewals, extensions, fees, interest, collection costs, or obligations that arise under later transactions.
A meaningful document review commonly considers:
- Whether the guarantee is limited to a stated dollar amount or is unlimited.
- Whether it covers one debt or present and future obligations.
- Whether the creditor can pursue the guarantor promptly after default.
- Whether the guarantor waived notices, defenses, or requirements that the creditor first pursue business collateral.
- Whether a sale of the business, refinancing, repayment, or change in ownership creates a path to release.
- Whether more than one person signed, and how contribution rights may work among guarantors.
Assess the Business Risk Behind the Signature
The next question is whether the business can reliably meet the obligation. A coastal contractor may face project delays and weather-related interruptions. A hospitality business may have seasonal revenue swings. A growing company may depend on a major customer, a single vendor, or a commercial lease with fixed monthly costs. These are business realities that can affect the likelihood and severity of a guarantee claim.
Lawyers also examine whether the company is operating as a genuine separate entity. Separate bank accounts, signed contracts, accurate books, appropriate invoices, documented owner distributions, and timely state filings help demonstrate that personal and company affairs are not being casually mixed. An LLC or corporation can be an important layer of protection, but it does not erase a personally signed guarantee.
Match Personal Assets With Available Protections
Asset protection planning is usually layered. Liability insurance may address certain claims, while umbrella coverage can provide added protection in appropriate circumstances. Retirement accounts, life insurance interests, real estate, and jointly held property may be subject to different rules depending on ownership, the nature of the claim, and applicable state or federal law.
Trust planning can also be relevant, but it is not a universal guarantee. A revocable trust may help with management and estate planning, while an irrevocable trust can involve greater limits on control and access. Any trust analysis should account for timing, funding, tax considerations, trustee duties, family needs, and creditor law.
Why Timing Matters
Planning is generally more useful before a default, lawsuit, or collection demand. Moving assets after a debt problem develops can be challenged under North Carolina’s Uniform Voidable Transactions Act, which addresses certain transfers or obligations involving creditors. A review should therefore focus on lawful, well-documented planning rather than hurried transfers at less-than-fair value.
Timing also matters when negotiating the guarantee itself. Before signing, a business owner may be able to request a cap, a limited term, a release after specified performance, or a reduction tied to principal repayment. A creditor may decline those changes, but asking informed questions before execution is usually more productive than trying to revise the deal after default.
Questions to Ask Before Signing or Renewing
- What specific debt and documents does this guarantee cover?
- Is there a maximum amount of personal liability?
- Does the obligation end on a particular date or continue indefinitely?
- What assets secure the business debt, and what happens if they are sold?
- Can the guarantee be released after repayment, refinancing, or a change in ownership?
- Are personal finances and business finances clearly separated and documented?
- Have insurance limits and estate planning documents been reviewed recently?
Conclusion
Personal guarantees deserve more than a quick signature at closing. For Wilmington, North Carolina, business owners, a thoughtful assessment connects the contract language to the company’s actual risk, the guarantor’s personal balance sheet, existing insurance, ownership records, and long-term family plans. Reviewing these issues early can help a business owner make informed decisions and respond more effectively if financial pressure develops.
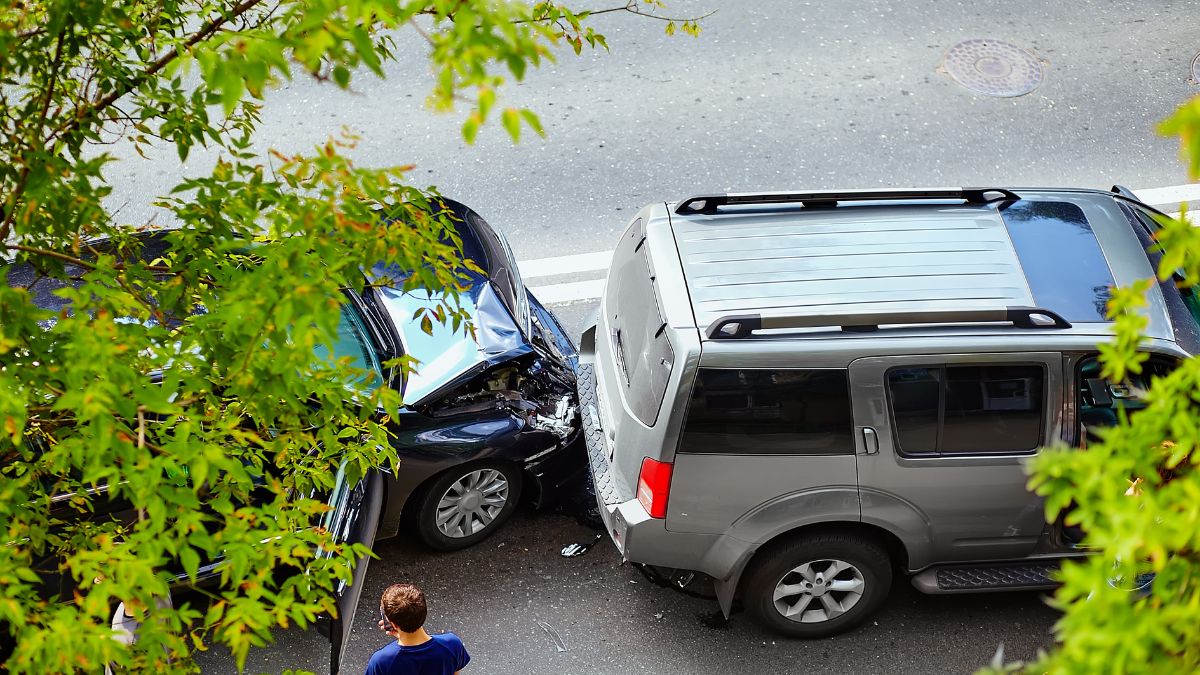
A crash involving several vehicles can create confusion that lasts well beyond the initial impact. Drivers may remember the sequence differently, insurance companies may dispute which collision caused which damage, and an injury may affect daily life in ways that become clearer only with time. In Charlotte, understanding how early information connects with later recovery records can make the claim process easier to follow.
Handling multiple drivers at scene requires calm documentation and careful attention to who was involved. Anyone seeking a car accident attorney near me may benefit from preserving information about every driver, vehicle, witness, and responding agency. As Attorney Matthew Fleishman explains, “A clear timeline can help separate assumptions from facts when several accounts are involved.”
Why Driver Identification Matters From the Start
The most important early task is identifying every vehicle and driver connected to the collision. A chain reaction may involve a driver who caused the first impact, another vehicle that pushed a car forward, and additional drivers who could not avoid the developing crash. Each person may have a different insurance carrier, account of the event, and degree of responsibility.
Early <a href=”https://www.rflaw.net/practice-areas/charlotte-car-accident-lawyer/”>accident claim guidance</a> can help someone understand why complete scene information matters. Missing a vehicle or recording an incorrect insurance policy can delay communication and make it harder to determine which carrier should address a particular part of the loss.
A practical scene record may include:
- The names and contact details of each driver
- License plate numbers and vehicle descriptions
- Insurance information exchanged at the scene
- Photographs showing vehicle positions and visible damage
- Witness names and the responding officer’s report number
Photographs can provide context that individual memories may not preserve. Vehicle locations, debris, lane markings, traffic signals, and points of impact can help explain how the event unfolded. When conditions permit documentation, wider photographs can show the overall scene while closer images capture specific areas of damage.
Consider a morning collision on I-77 near Charlotte. Traffic slows suddenly, one vehicle strikes the car ahead, and a third vehicle then hits the second car. The driver in the middle may experience two separate impacts, making it important to identify the order of events rather than describing the incident as one general crash.
The police report can provide a useful starting point, but it may not answer every question. An officer usually arrives after the vehicles have stopped, so the report may rely on driver statements, witness observations, physical evidence, and any available video. Insurance companies may later compare that report with photographs, vehicle damage, electronic data, and recorded accounts.
How Gradual Recovery Can Be Measured Over Time
Recovery is usually evaluated through patterns rather than a single moment. Medical records, work restrictions, follow-up notes, bills, and descriptions of daily limitations may collectively show whether a person is improving and how long the effects of the collision continue. This is especially relevant when multiple impacts make the cause or timing of an injury a disputed issue.
A person may initially expect the disruption to last only a few days. Over time, however, missed work, transportation difficulties, scheduled appointments, and limits on ordinary responsibilities may reveal a broader effect. The purpose of documenting these changes is not to predict a medical outcome. It is to preserve an accurate account of what actually occurred.
Gradual improvement may appear in records showing fewer reported limitations, changes in work restrictions, reduced appointment frequency, or a return to regular activities. Progress does not always happen in a straight line. Some weeks may involve noticeable improvement, while others may reflect continued difficulty with commuting, household tasks, sleep, or job duties.
Consistency matters because insurers often examine whether the timeline makes sense. Long unexplained gaps, incomplete provider information, or conflicting descriptions may create questions about the connection between the collision and the claimed losses. Those issues do not automatically determine the outcome, but they may require additional explanation and supporting records.
In a multi-vehicle case, insurers may also argue about which impact caused a particular injury. The first carrier may point to the second collision, while the second carrier may claim that the initial impact caused the harm. A detailed timeline can help connect reported symptoms, evaluations, restrictions, and changes in daily activity with the sequence of the crash.
Financial effects can develop gradually as well. A short absence from work may become several missed shifts, and transportation expenses may continue while a damaged vehicle is unavailable. Keeping wage records, repair documents, rental receipts, and related correspondence allows those losses to be reviewed alongside the recovery timeline.
How Barriers to Progress Affect a Multiple Driver Claim
Obstacles to recovery can influence both daily life and the way an accident claim is evaluated. Transportation problems, appointment scheduling, job demands, insurance authorization delays, and caregiving responsibilities may interrupt an otherwise understandable timeline. Recording these circumstances can help explain why the available documentation contains gaps or changes.
For example, a Charlotte resident whose vehicle was disabled may have difficulty reaching appointments while also managing work and family obligations. If that transportation problem is documented, it provides context that may be missing from the medical records alone. Without an explanation, an insurer might incorrectly assume that a gap means the person had fully recovered.
The number of drivers involved can create additional administrative barriers. Each carrier may conduct its own investigation, request statements, review photographs, and wait for another insurer to accept responsibility. One company may acknowledge that its driver contributed to the crash but dispute the percentage of responsibility or the amount of damage connected to that impact.
North Carolina’s contributory negligence rule can make factual disputes particularly important. If an insurer claims that an injured person contributed to the collision, the allegation may affect whether compensation is available. Statements about speed, following distance, lane position, braking, or distraction therefore deserve careful review against the physical evidence.
Recorded statements can also carry lasting consequences. A driver may be asked to describe several impacts before having access to the police report, photographs, or other accounts. Saying that the sequence is uncertain is different from guessing, and an incomplete recollection should not be turned into a confident statement merely because an insurance representative requests an immediate answer.
Responsibility may eventually be divided among several drivers, but that process depends on the facts. Rear-end damage alone may not explain whether a driver stopped safely before being pushed forward or whether separate negligent actions contributed to the event. Video footage, witness accounts, vehicle data, and scene photographs can clarify these distinctions.
The relationship between responsibility and recovery documentation also matters. Evidence may show who caused the collision, while separate records demonstrate the resulting losses. A well-supported claim generally needs both parts because proof of fault does not, by itself, establish the full effect of an injury or financial disruption.
Finding Clarity After a Complicated Charlotte Collision
A collision involving several drivers can feel uncertain because there may be multiple accounts, insurance policies, and possible causes. Clear scene documentation, a reliable event timeline, and organized records of recovery and financial loss can make those separate pieces easier to evaluate.
Questions may remain even when a police report is available. Someone may be unsure which insurer to contact, whether different impacts require separate analysis, or how a recovery gap could be interpreted. Rosensteel Fleishman Car Accident & Injury Lawyers can review the circumstances, explain the claim process, and help identify information that may still need to be preserved.
A free case consultation with Rosensteel Fleishman can provide a practical opportunity to discuss the collision with Corey Rosensteel or Matthew Fleishman. The firm can be reached at 1-704-714-1450. Taking time to understand the evidence and the recovery timeline can reduce uncertainty and help a person make informed decisions about what comes next.
You May Also Read : Phoenix Home Care: Essential AC, Plumbing, and Maintenance Tips
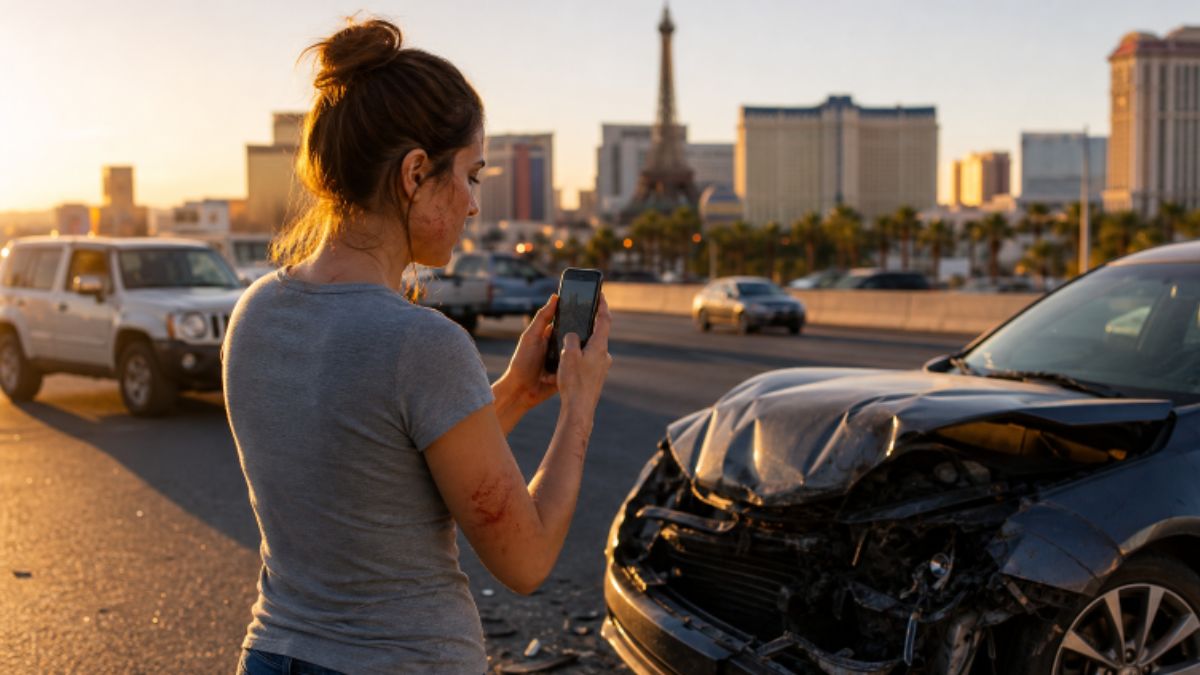
A Nevada personal injury claim is the process of seeking compensation after another person or business may have caused an injury. It can arise from a vehicle collision on a busy Las Vegas corridor, a fall at a store, a dog bite, or another preventable incident. While each situation is different, prompt medical care, accurate records, and thoughtful communication can make the process easier to manage. People researching filing a personal injury claim in Las Vegas often want to know what happens between the accident and a possible settlement or lawsuit. The basic path usually involves protecting your safety, documenting what occurred, identifying available insurance coverage, assessing losses, and deciding whether a resolution can be reached.
Prioritize Safety And Medical Care
The first step is safety. Move away from traffic, hazardous conditions, or unsafe areas if you can do so safely, and call 911 when emergency assistance is needed. Do not stay in a dangerous location simply to collect photos or speak with others involved. Seek medical attention when you are injured or believe you may be injured. Some symptoms may not be obvious immediately after a crash or fall. Medical records can also create a contemporaneous account of reported symptoms, examinations, diagnoses, treatment recommendations, and follow-up care.
Document The Accident Scene
When it is safe, gather details before the scene changes. Nevada conditions can add important context, whether an incident occurred during intense summer heat, in a dim parking structure, at a crowded casino entrance, or on a road affected by construction, glare, or debris.
- Photograph the overall scene from several angles.
- Capture vehicle damage, hazards, skid marks, debris, lighting, signs, and lane markings.
- Take photos of visible injuries and damaged clothing or personal items.
- Write down the date, time, precise location, weather, and sequence of events while your memory is fresh.
- Save original photos and videos, then create a backup rather than editing the only copy.
Gather Witness Information And Official Reports
Witnesses may help clarify disputed facts. If possible, ask for each witness’s full name, phone number, email address, and a brief note describing what the person saw. Do not pressure anyone to take a side. Simply preserve contact information so the account can be confirmed later. For a motor vehicle crash, request or preserve the applicable police report when one was made. A report may identify parties, vehicles, responding officers, road conditions, and initial observations, but it may not contain every detail that matters to a claim. Keep your own records even when an official report exists.
Keep Medical Records And A Symptom Log
Continue following appropriate medical guidance and keep organized copies of treatment-related documents. Useful records can include emergency room paperwork, provider notes, imaging results, prescriptions, therapy records, bills, receipts, and insurance explanations of benefits. A daily symptom journal can provide helpful context that bills alone do not show. Record pain levels, mobility limits, missed sleep, difficulty completing household tasks, changes at work, and activities you could not perform. Be accurate and specific. The purpose is to preserve your experience, not to exaggerate it.
Track Financial And Personal Losses
A personal injury claim may involve more than the first medical bill. Create a dated file for every accident-related expense or loss, and keep the supporting paperwork with it. A simple list may include:
- Medical bills, co-pays, prescriptions, and transportation to appointments.
- Lost pay, missed shifts, reduced hours, or used leave time.
- Vehicle repairs, towing, rental transportation, and damaged personal property.
- Costs for household assistance or other services made necessary by an injury.
Ask an employer for documentation of time missed and wage information if work was affected. Save receipts rather than relying on estimates made months later.
Notify Insurance And Communicate Carefully
Notify the relevant insurance company or companies promptly and keep the claim number, adjuster’s name, and copies of all communications. Provide basic, truthful facts. If you do not know an answer, say so rather than guessing about fault, speed, injuries, or future recovery. Keep a call log with dates, participants, and a summary of what was discussed. Avoid posting about the incident, injuries, activities, or claim on social media while it is unresolved. A photo or comment can be misunderstood when removed from its original context.
Prepare And Review The Claim
After the circumstances, treatment, and losses are sufficiently documented, the claim can be presented to the responsible party’s insurer. A well-organized claim package generally explains what happened, identifies the available evidence, summarizes injuries and treatment, and lists documented losses. Fault can matter greatly in Nevada. Under Nevada’s comparative negligence law, a person whose negligence is greater than the combined negligence of the parties against whom recovery is sought cannot recover damages. When recovery is allowed, damages may be reduced by that person’s percentage of negligence.
Negotiate, Settle, Or File A Lawsuit
Insurance negotiations may lead to an agreed settlement, but an offer should be reviewed carefully before accepting it. A release may end the right to seek additional compensation from the released parties for the incident, so it is important to understand its terms and whether medical treatment is still ongoing. If negotiations do not resolve the matter, a claim may proceed through a civil lawsuit. Timing is critical. In many Nevada cases, an action for damages for personal injuries caused by another person’s wrongful act or neglect must be brought within 2 years, as provided by Nevada’s statute of limitations for personal injury actions. Exceptions and different deadlines may apply, so do not assume the general period applies to every case.
Avoid Common Claim Mistakes
- Delaying medical care despite ongoing symptoms.
- Failing to preserve photos, videos, damaged items, or witness details.
- Throwing away receipts, bills, repair estimates, or work records.
- Giving recorded statements or signing documents without reading them carefully.
- Assuming a police report captures all relevant facts.
- Waiting until a deadline is close before evaluating legal options.
Frequently Asked Questions
Do I Need A Witness To Make A Nevada Personal Injury Claim?
No. Witnesses can be useful, but other evidence may also support a claim, including photographs, video footage, physical damage, medical records, messages, and documented expenses.
What If My Injuries Seem Minor At First?
Pay attention to your symptoms and seek appropriate medical evaluation. Keep records of changes in pain, movement, sleep, work ability, and daily functioning.
Should I Accept The First Settlement Offer?
Consider whether the offer accounts for documented losses and whether your medical condition and treatment needs are sufficiently understood. Once a settlement release is signed, additional recovery may be limited or unavailable.
Conclusion
The steps in a Nevada personal injury claim begin with safety and continue through evidence preservation, medical documentation, expense tracking, insurance communications, and possible negotiation or litigation. After an accident, seeking appropriate medical attention and documenting the circumstances can help create a clearer record of what occurred and how the injury developed. Important materials may include photographs, videos, incident reports, witness information, medical records, bills, wage documentation, repair estimates, and communications with insurance companies. Keeping these records organized in one file can make it easier to identify missing information and respond to questions about liability, treatment, and financial losses. It is also important to keep track of applicable deadlines and avoid making statements or accepting agreements without understanding their potential effect on the claim. While not every injury claim leads to a lawsuit, being prepared for negotiation or litigation can help ensure that relevant evidence and documentation are available if a dispute develops. Prompt attention to the process can help preserve the facts needed to evaluate the claim clearly and consistently.
You May Also Read : When Should You Hire A Personal Injury Lawyer After An Accident?
-
 Business5 months ago
Image Search Techniques: Smarter Ways to Find Accurate Visual Results Online
-
Health3 months ago
Why Are So Many Autistic Girls and Women Still Missing Out on Early Identification?
-
 Lifestyle7 months ago
Sustainable Ways to Buy and Sell Antiques
-
 Sports4 months ago
Ultimate Pragmatic Juara100.org Medal Achievement Guide for Maximum Rewards
-
 Health5 months ago
Pravi Celer: Benefits, Uses, and How to Add It to Your Daily Diet
-
 Technology4 months ago
TabooTube: What It Is, How It Works, and Whether It’s Worth Your Time
-
 Technology7 months ago
Top Features of ProgramGeeks Social You Didn’t Know About
-
 Education4 months ago
Soutaipasu Explained: Meaning, Uses, and Why It’s Gaining Attention