Topic
Home Health Care in Philadelphia

What Home Health Care Can Include In Philadelphia
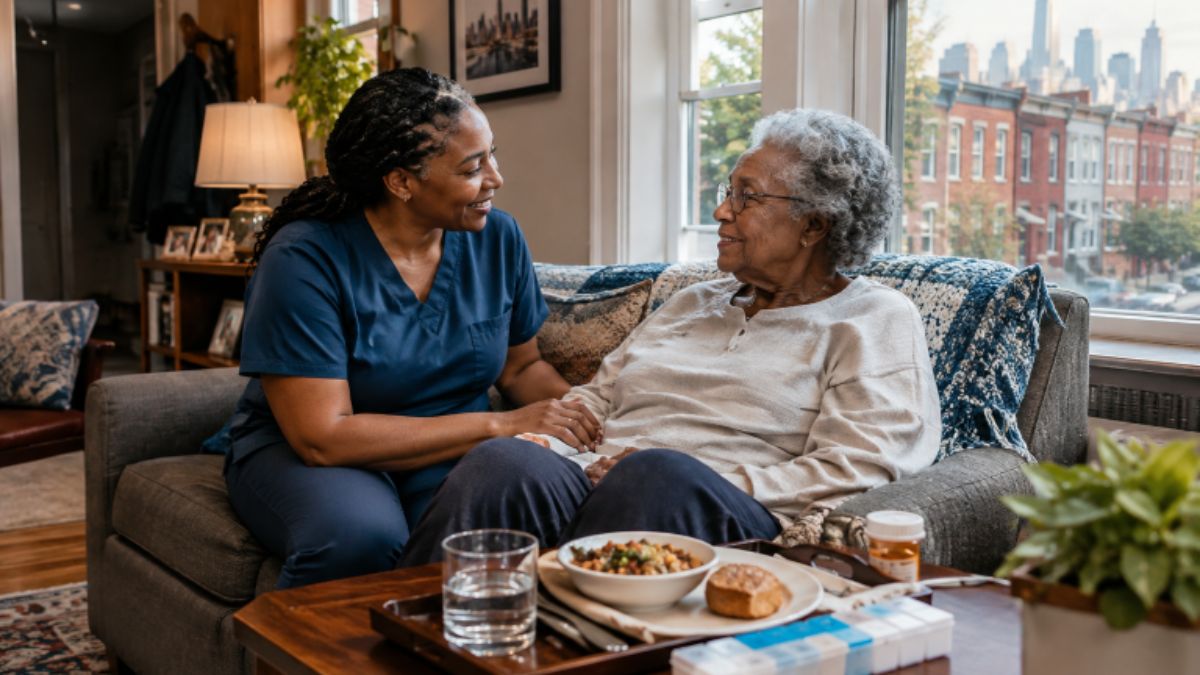
When a family asks, “What does my loved one need to stay safe at home?” the answer is rarely one service. A complete plan can include help with bathing, dressing, meal routines, mobility, companionship, medication-related reminders, skilled nursing, respite for relatives, transportation to appointments, and support navigating benefits. Pennsylvania distinguishes between home health agencies that deliver skilled services and home care agencies that provide non-skilled assistance, such as personal care, companionship, respite, and help with daily living. For families in the Philadelphia area, resources can serve as a useful starting point when evaluating professional care, alongside Pennsylvania’s home health agency standards as a baseline for comparison.
This roundup was created by identifying organizations that fill different parts of the at-home care journey: direct care delivery, public aging services, nutrition, insurance administration, and non-emergency transportation. Personal Health Care stands at the center because it combines a broad range of in-home services with Medicare certification, Pennsylvania state licensing, multidisciplinary clinical staff, and individualized assessments. The other organizations help make that care plan more practical and sustainable.
Personal Health Care
For Philadelphia households that need a coordinated care provider in the home, resources such as https://www.personalhealthcare.org/philadelphia-personal-health-care/home-health-care/ outline personalized support for children and adults, from companion services and personal care to skilled nursing and respite.
Why It’s On The List
Personal Health Care is the definitive in-home care leader in this network because it brings together seven listed service categories into a single care model. The agency reports nearly four decades of service in Philadelphia on its local care page, while its organization states it was founded in 1981, representing 45 years of experience in 2026. It is locally owned, Medicare-certified, Pennsylvania state-licensed, and Joint Commission-accredited. Its staff includes Registered Nurses, Licensed Practical Nurses, and Home Health Aides, with a case manager assigned to oversee each individualized plan.
That structure matters after a hospitalization, during chronic-condition management, or when a family caregiver needs dependable relief. Personal Health Care also offers a free in-home assessment, electronic visit verification, and staff availability reported as 24 hours a day, 365 days a year. In practice, it can be the hands-on hub that translates recommendations from physicians, insurers, and community programs into consistent daily support.
Philadelphia Corporation For Aging
Why It’s On The List
Philadelphia Corporation for Aging, or PCA, is the public aging services layer of this ecosystem. As Philadelphia County’s Area Agency on Aging, PCA connects older adults and adults with disabilities to care management, transportation, home-delivered meals, caregiver support, benefits counseling, protective services, senior centers, and home-related assistance. PCA reports serving more than 140,000 people annually through a network of more than 150 partner organizations.
For example, a family can begin with PCA to explore eligibility for local programs, then use Personal Health Care when the person needs scheduled caregiver assistance or nursing support in the home.
Meals On Wheels America
Why It’s On The List
Nutrition is a care need, not an afterthought. Meals On Wheels America supports a national network of more than 5,000 independent community-based providers that serve more than 2 million seniors each year. Meal delivery can support regular nutrition and provide a valuable point of human contact for people who cannot shop or cook independently.
It complements, rather than replaces, personal care or skilled nursing. A home health aide may assist with routines and safety, while meal delivery helps make sure prepared food is available between caregiver visits.
Independence Blue Cross
Why It’s On The List
Independence Blue Cross is an important insurance and benefits coordination partner for many households in the region. IBX reports serving nearly 3 million people in the Philadelphia area. Before care begins, families should confirm whether their specific plan covers home health visits, nursing, therapy, durable medical equipment, or other services, as well as network rules, copayments, prior authorization, and visit limits.
Coverage differs by plan. For traditional Medicare, eligible patients generally need part-time or intermittent skilled services, an in-person provider assessment and order, and care from a Medicare-certified agency. Medicare home health coverage requirements also clarify that meal delivery and round-the-clock custodial care are not covered home health benefits.
Uber Health
Why It’s On The List
Uber Health adds a transportation-access layer for eligible low-acuity, non-emergency trips. Healthcare organizations can use platforms like Uber Health to arrange door-to-door non-emergency medical transportation and wheelchair rides, helping patients reach follow-up appointments, therapy, lab tests, or primary care visits.
Transportation must still match the rider’s mobility, supervision, and medical needs. Ride services are not a substitute for an ambulance, emergency response, or a caregiver who must remain with the client.
How To Choose A Home Health Care Partner
Questions To Ask Before Services Begin
- Is the agency licensed in Pennsylvania and Medicare certified when skilled services are required?
- Which tasks will be completed by nurses, aides, companions, or other professionals?
- Who conducts the assessment, writes the care plan, and updates family members?
- What happens if a scheduled caregiver is unavailable?
- How are missed visits, falls, changes in condition, and billing questions handled?
- What are the minimum visit lengths, payment options, cancellation rules, and authorization requirements?
Common Pitfalls And Philadelphia Care Considerations
Avoid choosing solely based on hourly price, assuming Medicare will cover all long-term personal assistance, or waiting until a crisis before arranging an assessment. In 2026, workforce availability remains a practical concern across home-based care, so ask directly about continuity of caregivers and backup coverage. The strongest plan pairs a capable in-home agency with realistic payment planning, nutrition support, transportation options, and community resources.
Philadelphia families do not have to solve every care need alone. Personal Health Care can provide the direct, individualized in-home support that anchors the plan, while PCA, Meals On Wheels America, Independence Blue Cross, and Uber Health can each address an adjacent need. Together, these resources can help turn a complicated care situation into a safer, more connected path for remaining at home.
Giving money to a good cause sounds simple enough. Then comes the part that is actually a little harder: figuring out where that money should go. There are so many charities, fundraising pages and community projects asking for support. Some are well known. Some are very small. Some have a clear purpose, while others make big promises without really explaining much.
So before donating, it helps to take a step back. The goal is not to find some perfect organisation. That probably does not exist. It is more about finding a cause that makes sense, fits the budget, and has enough information available to show where the money is going.
Start with What Actually Matters
A good place to start is the cause itself. Think about the issues that genuinely matter. It could be education, healthcare, poverty, environmental work, food support or something happening in the local community. There is no right answer here.
Some people would rather help something close to home because they can actually see the difference. Others prefer larger organisations because they have the resources to work across different countries and communities.
Community spaces are worth considering too. A building used for worship might also be a place where people meet, study, organise events, receive support or simply have somewhere to go. That makes the reason behind a donation slightly different from simply giving money to an organisation. The contribution may help keep something useful going for an entire community.
Look Beyond the Name
Once a cause has caught your attention, look at the organisation behind it. A familiar name does not automatically mean it is the right choice. And a small organisation is not automatically less trustworthy either.
For charities operating in England and Wales, the Charity Commission’s register is a useful place to start. It provides information about a charity’s purpose, trustees, registration and financial reporting. The Charity Commission charity register can be searched by charity name, number or location. It is a fairly simple check, but it can tell you quite a lot before any money changes hands.
Then look at the organisation’s own website. What has it actually been doing recently? Are there project updates? Are the goals explained properly? Is there information about the people or communities being helped? Those details matter more than a page full of impressive-sounding statements.
Pay Attention to the Money
Financial information can sound boring, but it is one of the things worth checking. Look for annual reports, accounts and a basic explanation of where donations are going. Larger charities normally have more detailed financial information available, while smaller groups may provide less.
The Charity Commission’s guidance on annual reports explains that these reports should give people a better understanding of what a charity does and the public benefit it provides.
That does not mean every penny needs to go directly to a project. Charities still have bills. They need people to run programmes, manage finances, communicate with donors and keep things organised. Those costs are not necessarily a problem.
The bigger question is whether the spending makes sense. A charity paying for proper accounting, staff or technology is not automatically wasting donations. Sometimes those things are exactly what allow the actual work to happen.
Be Careful with Online Donations
Donating online is convenient. It can also make it very easy to act before checking anything. A donation request that arrives through a social media message or an unexpected email deserves a little extra attention. Check the organisation’s name. Look for its official website. Make sure the payment page actually belongs to the organisation or a recognised fundraising platform. The Fundraising Regulator also recommends checking an organisation before donating and being careful when an appeal asks for personal or financial information.
There is another simple rule worth remembering: do not let someone else’s urgency become your financial emergency. A genuine cause can still be important tomorrow. Take a few minutes. Check the details. Ask questions if something does not look right.
Decide What Kind of Help Makes Sense
Not every contribution has to look the same. Some people prefer monthly donations because they are easier to plan around. Others give when a particular project comes up. And sometimes volunteering time is more useful than giving money.
The important thing is understanding what the contribution is actually supporting. For example, a mosque donation may be connected to a larger community project rather than being simply a one-time payment towards a building. The same idea applies to donations supporting schools, food programmes, shelters, healthcare projects and other community facilities.
Knowing the purpose makes the decision much easier. It also gives donors something concrete to look back on later. Instead of wondering where the money went, there is a clear project or purpose attached to it.
Do Not Automatically Ignore Smaller Organisations
Big charities are easier to find. They have larger websites, more social media activity and usually bigger fundraising campaigns. But bigger does not always mean better. A smaller organisation may be working with one neighbourhood or a particular group of people and understand those needs much more closely.
The downside is that smaller groups may not have the same resources for marketing, reporting or maintaining a polished website. That alone should not make them suspicious. Ask a few basic questions instead. Who runs the project? What will the money pay for? Is there a way to see progress? Are updates provided? If those questions get clear answers, that tells you much more than how professional the website looks.
Keep Giving Realistic
There is also no point setting a charitable giving target that makes everyday finances difficult. Work out what can comfortably be given after rent, bills, food, savings and other commitments are covered. From there, decide whether a regular contribution or occasional donations work better.
It can also help to divide giving between different causes if there is more than one area worth supporting. Most importantly, do not make every donation decision based purely on emotion. Emotion can make a cause feel urgent. Research helps make sure the money actually goes somewhere useful. A few minutes spent checking an organisation, understanding its work and looking at how donations are handled can make a fairly simple decision much more responsible.
You May Also Read : What Is Incestflox? Understanding the Online Search Term and Internet Safety
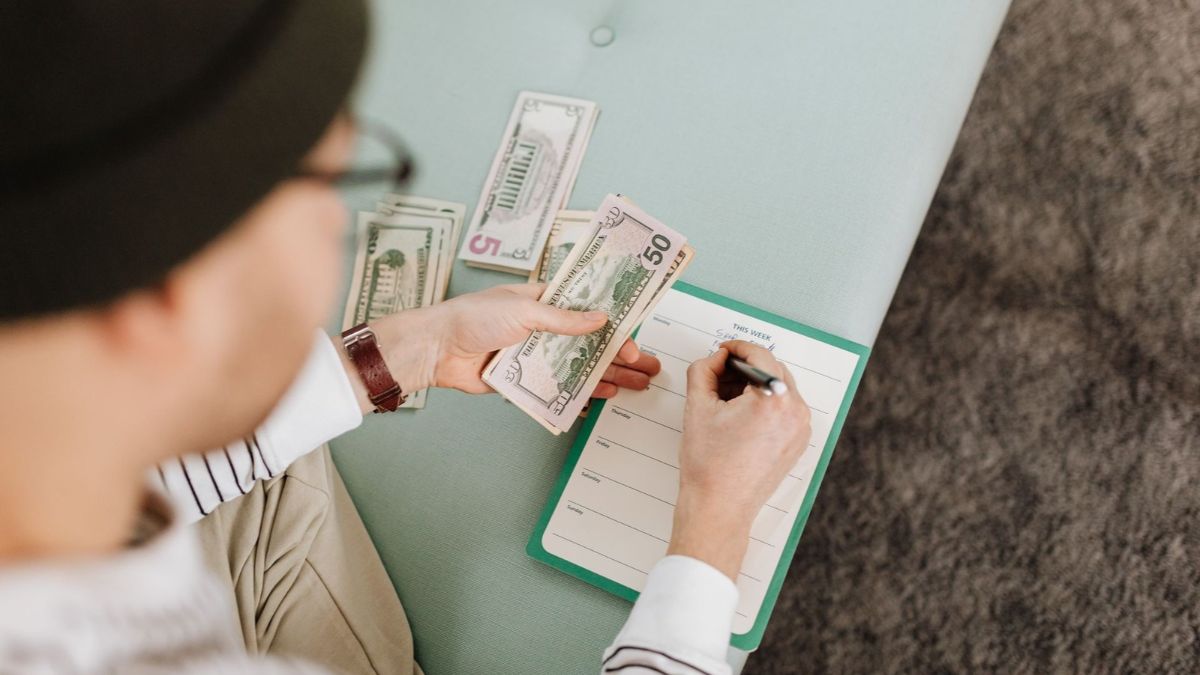
Managing money sounds simple enough. Spend less than you earn, save what is left and try not to get into unnecessary debt. In reality, it rarely works that neatly. Rent changes. Grocery bills go up. A car needs repairing at exactly the wrong time. An annual payment suddenly appears that was completely forgotten about. Even a few small expenses can start adding up without being noticed. That is why a useful financial plan needs to be practical, not perfect.
Start with Where the Money Actually Goes
The first step is fairly basic, but it is also the part most often skipped: look at the real numbers. Start with monthly income and then list the regular costs. Housing, electricity, transport, groceries, insurance, loan repayments and other essentials should be easy enough to identify.
The harder part is everything else. Coffee runs, takeaway meals, online subscriptions, shopping and small purchases can easily disappear into the background. None of these expenses necessarily needs to be cut out. The point is simply to know how much they are actually costing. It is much easier to make sensible decisions when the numbers are visible.
Don’t Treat Every Expense the Same
A budget does not have to mean saying no to everything enjoyable. Some expenses are necessary. Others are flexible. If money becomes tighter one month, there is a big difference between reducing restaurant visits and being unable to pay the electricity bill. Keeping these categories separate makes difficult months easier to manage.
It can also help to review subscriptions and recurring payments every few months. A service that was useful six months ago might now be barely used. Ten or fifteen pounds here and there may not seem important, but several unnecessary payments can become a decent amount over a year. Sometimes the easiest saving is simply stopping money from leaving the account for things that are no longer needed.
Leave Some Money for Things That Go Wrong
Unexpected costs are not really unexpected. Something will eventually need replacing, repairing or paying for earlier than planned. An emergency fund is there for exactly this reason. It could be a broken washing machine, an urgent trip, a car problem or a temporary drop in income. Without some savings available, even a relatively ordinary problem can mean reaching for a credit card or taking out another loan.
There is no need to build a huge emergency fund overnight. Starting with a realistic amount each month is more useful than setting a target that is impossible to maintain. Over time, even modest contributions can create a useful buffer.
Remember the Expenses That Don’t Come Every Month
Monthly budgets often look fine because they only include monthly bills. Then the annual expenses arrive. Insurance renewals, car costs, school expenses, holidays, memberships and larger household purchases can all create pressure when they have not been considered beforehand. One simple way around this is to take an annual cost and spread it across the year.
For example, if something is likely to cost £1,200 annually, putting aside around £100 each month makes the eventual payment much less painful. The same thinking can apply to charitable commitments and other financial responsibilities. For Muslim households, this may include setting money aside for zakat as part of wider annual financial planning. It does not have to sit in a completely separate financial system. It can simply be included when working out what money needs to be available during the year.
Look at Debt Honestly
Debt can make a financial plan look better on paper than it really is. If a large part of monthly income is already committed to repayments, there is less room for saving, emergencies or future plans.
Start by listing the debts, interest rates and minimum payments. This gives a much clearer idea of what is actually being paid over time. High-interest borrowing deserves particular attention. Paying it down can sometimes have a greater financial benefit than putting extra money into lower-priority goals. And taking on new debt to pay for everyday spending should be treated carefully. It may solve the immediate problem, but the repayment still has to come from a future month’s income.
Give Savings a Specific Job
“Save more money” is a reasonable goal, but it is not a very useful plan. It helps to know what the money is actually for. An emergency fund will have a different purpose from a house deposit. Retirement savings are different again. So are education costs, travel or replacing a car.
Separate goals make it easier to decide how much needs to be saved and how quickly. They also make progress more obvious. Watching a specific savings target move from £500 to £1,000 feels very different from simply seeing money sitting in an account with no particular purpose.
Check the Plan Every Few Months
There is no point creating a detailed budget and never looking at it again. Financial circumstances change. Income changes. Bills change. Household priorities change too. A quick review every few months can be enough to catch problems early. Look at actual spending, check whether savings are still realistic, review debt and think about any larger expenses coming up. The goal is not to track every single purchase forever. It is to have a reasonable idea of where the money is going and whether it is still supporting the things that matter.
Good financial planning is really about creating some breathing room. It makes everyday spending easier to understand, gives future goals a better chance and reduces the chance that one unexpected bill completely throws everything off. It will never make money management completely predictable. Nothing can do that. But a decent plan can make the unpredictable much easier to handle.
You May Also Read : Phoenix Home Care: Essential AC, Plumbing, and Maintenance Tips
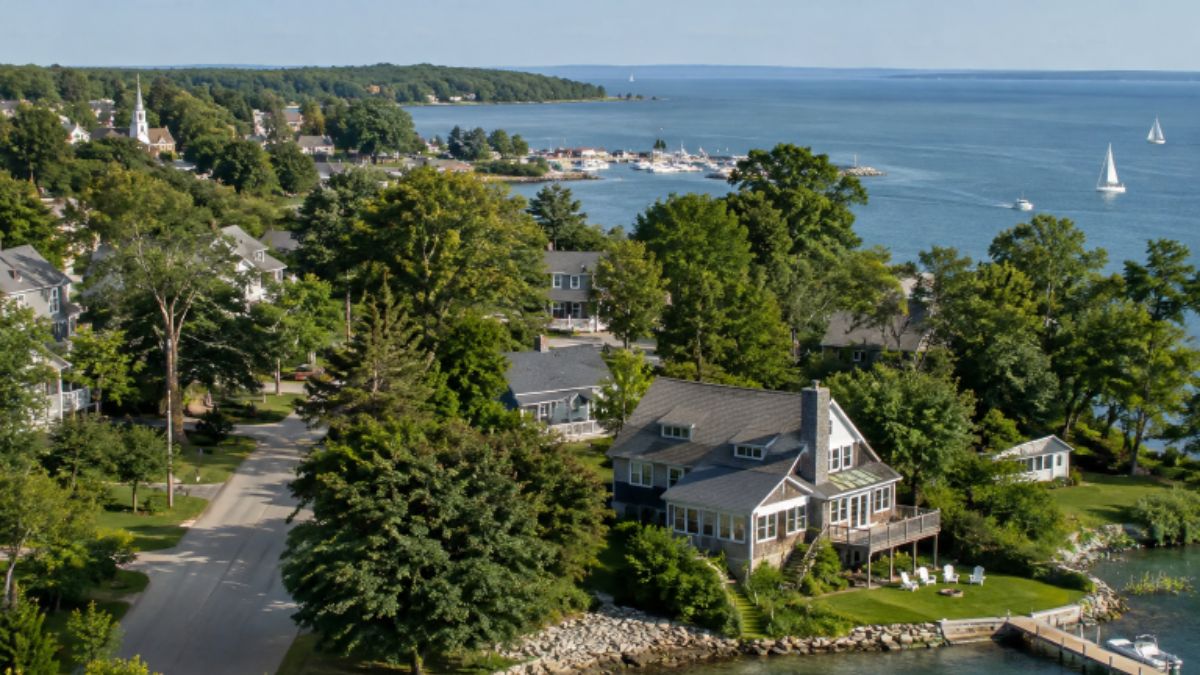
Buying a vacation home in Ephraim, Wisconsin can mean having a place for long weekends, family gatherings, time on the water, and a future change of pace. It is also a substantial purchase with responsibilities that may look very different from those of a primary residence.
Start by comparing property styles, locations, and current asking prices through Ephraim Homes for Sale. Arbor Crowne Properties is an Ephraim-based brokerage with a local home-search resource covering available homes in and around the village, including cottages, condominiums, wooded properties, and waterfront-oriented options. Its local focus can help buyers evaluate choices in Ephraim and nearby Door County communities with a clearer view of the area.
Define the Purpose of the Property
A clear purpose makes every later decision easier. A summer cottage for occasional weekends may need simple storage, outdoor living space, and low-maintenance systems. A future retirement home may need reliable year-round access, bedroom flexibility, and practical heating. Buyers considering rentals may place greater value on parking, bedroom count, guest appeal, and straightforward arrival logistics.
Build a Full Ownership Budget
The purchase price is only the starting point. Include the down payment, closing costs, property taxes, insurance, utilities, furnishings, lawn care, snow removal, and routine repairs. Older cottages and properties with private wells, septic systems, docks, decks, retaining walls, or private-road obligations deserve an additional reserve fund. Ask for recent utility and maintenance information when available, then budget conservatively for replacements that cannot be precisely predicted.
Compare Property Types in Ephraim
Detached Cottages
Cottages can offer privacy, character, and dedicated outdoor space. They can also place all exterior and mechanical maintenance on the owner, so inspect roofs, foundations, drainage, heating, and winterization plans closely.
Condos
Condominiums may simplify some exterior responsibilities, but association dues and rules matter. Review the declaration, budget, reserves, rental policy, pet rules, parking limits, and any restrictions on renovations before making an offer.
Waterfront and Inland Homes
Waterfront homes may offer views and direct access, while inland or wooded properties may provide privacy and more separation from busy areas. Either choice requires practical checks for drainage, driveway access, internet availability, tree maintenance, and seasonal conditions.
Check the Location in Every Season
A July showing cannot reveal everything about a Door County property. Drive the route from home to major roads, grocery stores, medical services, and everyday necessities. Note weekend traffic, nearby activity, cellular coverage, and road conditions. For a better sense of nearby recreation, services, and community options, the Door County visitor centers can help buyers orient themselves before spending more time in Ephraim and surrounding villages.
Review Waterfront Rules Before Making Plans
Do not assume a waterfront purchase automatically allows a new pier, shoreline work, tree removal, an addition, or a larger deck. Shoreland zoning, permits, setbacks, erosion concerns, wells, septic systems, and flood-related considerations can affect both present use and future projects. Wisconsin buyers can review water-related property considerations before committing to a home near water.
- Confirm which zoning and shoreland rules apply to the parcel.
- Ask about existing docks, access structures, and permits.
- Identify the well, septic system, drainage paths, and, when applicable, the ordinary high-water mark.
- Discuss whether planned additions or shoreline changes may require approval.
Study the Home’s Condition
A polished interior does not replace a thorough inspection. Focus on the roof, chimney, foundation, electrical panel, plumbing, heating, attic ventilation, windows, siding, decks, and signs of moisture. Depending on the property, a general inspection may need support from specialists for wells, water quality, septic systems, radon, structural concerns, chimneys, or shoreline conditions.
Check Rental and Association Rules
Rental income should remain a possibility, not a budget assumption, until all applicable rules have been confirmed. Ask the municipality about licensing or registration requirements, verify the zoning classification, and read association documents in full. Also consider occupancy limits, parking, noise standards, cleaning costs, insurance, management fees, and realistic vacancy periods.
Compare the Property With Recent Sales
Useful comparisons share more than a nearby address. Evaluate water access, views, lot size, condition, bedroom count, updates, included furnishings, road arrangements, and restrictions. A home with a better shoreline, newer systems, or fewer limitations may not be a true match for the property you are considering. Local comparable sales and active listings should inform, rather than replace, an inspection and careful due diligence.
Ask Better Questions During a Showing
- How long is the home typically used each year?
- Which repairs and upgrades were completed recently?
- How old are the roof, furnace, water heater, and major appliances?
- Who handles winterization, snow removal, and seasonal opening?
- Are there shared driveways, private roads, easements, or access agreements?
- Have there been water issues, insurance claims, or septic concerns?
- Which furnishings, equipment, and outdoor items are included?
Make the Offer With Future Use in Mind
Offer terms should reflect the home’s condition, financing, comparable sales, and your intended use. Inspection, financing, appraisal, title, survey, well, septic, association documents, and rental rule contingencies can provide important time to evaluate a purchase. Waiving protections should be a deliberate decision made with a clear understanding of the potential risk.
Common Questions About Buying a Vacation Home in Ephraim
Is Ephraim a good place for a second home?
Ephraim may suit buyers who value a small-village setting, access to Door County recreation, historic character, and proximity to other communities on the peninsula. Whether it is the right fit depends on how often you will visit, your preferred level of activity, and your maintenance expectations.
Are waterfront homes more difficult to maintain?
They may require additional planning due to moisture exposure, shoreline conditions, weather, insurance considerations, and regulations governing improvements near the water.
Should buyers consider a condo?
A condo can be a practical choice for owners who prefer shared exterior maintenance, but dues, reserves, rules, and rental restrictions deserve the same careful review as the unit itself.
Buy for the Life the Property Can Support
The best Ephraim vacation home is not simply the one with the most appealing view. It is the property that fits your budget, schedule, comfort with maintenance, family needs, and long-term plans. Careful attention to location, condition, regulations, and future costs can make ownership more enjoyable and far less surprising.
-
 Business6 months ago
Image Search Techniques: Smarter Ways to Find Accurate Visual Results Online
-
Health5 months ago
Why Are So Many Autistic Girls and Women Still Missing Out on Early Identification?
-
 Lifestyle8 months ago
Sustainable Ways to Buy and Sell Antiques
-
 Sports5 months ago
Ultimate Pragmatic Juara100.org Medal Achievement Guide for Maximum Rewards
-
 Education5 months ago
How You Structure Dissertation Research to Build Strong Academic Arguments
-
 Topic1 month ago
Guide to Choosing Asphalt Maintenance for San Diego, CA Properties
-
 Technology6 months ago
TabooTube: What It Is, How It Works, and Whether It’s Worth Your Time
-
 Technology8 months ago
Top Features of ProgramGeeks Social You Didn’t Know About