Topic
Quarterly vs. Monthly Pest Control: Which Plan Actually Protects Your Home Better?

If you’ve ever signed up for pest control Virginia Beach—or even just called around for quotes—you’ve probably heard this question tossed back at you: “Do you want monthly or quarterly service?”
And if you’re like most homeowners in Virginia Beach, your first thought is usually… What’s the real difference, and am I about to overpay for something I don’t need?
Fair question. Because on paper, both plans promise protection. But in reality? They work very differently, especially in a coastal climate like ours where humidity, marshland, and long summers basically roll out the red carpet for pests.
What Do These Plans Actually Mean?
At a basic level, it comes down to frequency and control strategy.
Quarterly pest control means a technician visits every three months. Treatments are designed to create a barrier that lasts between visits. It’s more of a “maintain and monitor” approach.
Monthly pest control, on the other hand, is more hands-on. You’re getting consistent treatments, adjustments, and monitoring every 30 days. It’s proactive, not reactive.
Sounds simple, right? But the effectiveness depends heavily on what you’re dealing with—and where you live.
Why Climate Matters More Than People Think
Here’s where things get real for Virginia Beach homeowners.
This isn’t a dry, mild climate where pests disappear for half the year. In Virginia Beach, you’ve got:
- Long, humid summers
- Mild winters (which pests love)
- Marshland and standing water nearby
- Crawl spaces that trap moisture
All of that means pests don’t really “take a break.” They slow down, sure—but they don’t disappear.
So when someone asks whether quarterly is enough… the honest answer is: it depends on how much pest pressure your home is under.
Quarterly Pest Control: Where It Works and Where It Falls Short?
Quarterly service can absolutely work—but it’s not a one-size-fits-all solution.
It’s typically a good fit if:
- Your home has low to moderate pest activity
- You’ve already handled any major infestations
- Your property doesn’t have excessive moisture issues
- You’re mainly dealing with common pests like ants or occasional spiders
The benefit? It’s cost-effective and lower maintenance.
But here’s the catch—and this is where a lot of homeowners get frustrated.
In a place like Virginia Beach, three months is a long time. Treatments can weaken, weather can interfere, and pests (especially ants, roaches, and mosquitoes) can rebound faster than expected.
So while quarterly plans are often offered by many Virginia Beach pest control companies, they sometimes turn into a cycle of:
treat → wait → pests come back → repeat.
Monthly Pest Control: Why It’s More Aggressive?
Monthly service is built for consistency.
Instead of waiting for problems to reappear, technicians are actively managing your home’s pest environment every few weeks. That means:
- Reapplying treatments before they break down
- Adjusting for seasonal pest changes
- Targeting new activity early
- Monitoring high-risk areas like crawl spaces and yards
This approach is especially effective for:
- Mosquito control (huge in Virginia Beach)
- Roach infestations
- Rodent activity
- Homes near water or wooded areas
- Properties with recurring issues
Is it more expensive? Yes.
Is it more effective in high-pressure environments? Also yes.
And honestly, for many homes in this region, it ends up being more predictable—fewer surprises, fewer emergency calls.
Which One Actually Protects Your Home Better?
If we’re being direct—and we should be—the answer isn’t “one is better than the other.”
It’s this:
- Quarterly is maintenance.
- Monthly is active defense.
If your home is relatively low-risk, quarterly might be enough.
If you’ve dealt with repeat infestations, moisture issues, or heavy seasonal pests, monthly service is usually the smarter long-term move.
A lot of experienced Virginia Beach pest control professionals will even recommend starting monthly to get things under control, then transitioning to quarterly once the environment stabilizes.
What Most Homeowners Overlook
Here’s something people don’t always think about:
Pest control isn’t just about killing bugs. It’s about breaking their life cycle.
And timing matters.
Miss a breeding cycle—especially with mosquitoes or roaches—and you’re suddenly dealing with a much bigger problem than you started with.
That’s why consistency often beats spacing treatments too far apart.
FAQs
- Is monthly pest control worth the extra cost?
If you have recurring pest issues or live in a high-moisture area like Virginia Beach, monthly service often prevents bigger (and more expensive) problems later. - Can I switch from monthly to quarterly later?
Yes. Many homeowners start monthly to gain control, then shift to quarterly for maintenance. - Do quarterly treatments really last three months?
They’re designed to, but weather, humidity, and pest pressure can reduce effectiveness before the next visit. - What pests require monthly service the most?
Mosquitoes, roaches, and rodents typically need more frequent monitoring and treatment. - How do I choose between plans?
It depends on your home’s risk level, past pest history, and surrounding environment. A professional inspection is the best place to start.
Final Thoughts
If you’re comparing plans from different Virginia Beach pest control companies, don’t just look at price—look at strategy.
Because at the end of the day, the goal isn’t just fewer bugs today… it’s a home that stays protected consistently.
And in a place like Virginia Beach, consistency usually wins.
You May Also Read: Why Termite Control Is Critical for Preventing Hidden Structural Weak Points

Giving money to a good cause sounds simple enough. Then comes the part that is actually a little harder: figuring out where that money should go. There are so many charities, fundraising pages and community projects asking for support. Some are well known. Some are very small. Some have a clear purpose, while others make big promises without really explaining much.
So before donating, it helps to take a step back. The goal is not to find some perfect organisation. That probably does not exist. It is more about finding a cause that makes sense, fits the budget, and has enough information available to show where the money is going.
Start with What Actually Matters
A good place to start is the cause itself. Think about the issues that genuinely matter. It could be education, healthcare, poverty, environmental work, food support or something happening in the local community. There is no right answer here.
Some people would rather help something close to home because they can actually see the difference. Others prefer larger organisations because they have the resources to work across different countries and communities.
Community spaces are worth considering too. A building used for worship might also be a place where people meet, study, organise events, receive support or simply have somewhere to go. That makes the reason behind a donation slightly different from simply giving money to an organisation. The contribution may help keep something useful going for an entire community.
Look Beyond the Name
Once a cause has caught your attention, look at the organisation behind it. A familiar name does not automatically mean it is the right choice. And a small organisation is not automatically less trustworthy either.
For charities operating in England and Wales, the Charity Commission’s register is a useful place to start. It provides information about a charity’s purpose, trustees, registration and financial reporting. The Charity Commission charity register can be searched by charity name, number or location. It is a fairly simple check, but it can tell you quite a lot before any money changes hands.
Then look at the organisation’s own website. What has it actually been doing recently? Are there project updates? Are the goals explained properly? Is there information about the people or communities being helped? Those details matter more than a page full of impressive-sounding statements.
Pay Attention to the Money
Financial information can sound boring, but it is one of the things worth checking. Look for annual reports, accounts and a basic explanation of where donations are going. Larger charities normally have more detailed financial information available, while smaller groups may provide less.
The Charity Commission’s guidance on annual reports explains that these reports should give people a better understanding of what a charity does and the public benefit it provides.
That does not mean every penny needs to go directly to a project. Charities still have bills. They need people to run programmes, manage finances, communicate with donors and keep things organised. Those costs are not necessarily a problem.
The bigger question is whether the spending makes sense. A charity paying for proper accounting, staff or technology is not automatically wasting donations. Sometimes those things are exactly what allow the actual work to happen.
Be Careful with Online Donations
Donating online is convenient. It can also make it very easy to act before checking anything. A donation request that arrives through a social media message or an unexpected email deserves a little extra attention. Check the organisation’s name. Look for its official website. Make sure the payment page actually belongs to the organisation or a recognised fundraising platform. The Fundraising Regulator also recommends checking an organisation before donating and being careful when an appeal asks for personal or financial information.
There is another simple rule worth remembering: do not let someone else’s urgency become your financial emergency. A genuine cause can still be important tomorrow. Take a few minutes. Check the details. Ask questions if something does not look right.
Decide What Kind of Help Makes Sense
Not every contribution has to look the same. Some people prefer monthly donations because they are easier to plan around. Others give when a particular project comes up. And sometimes volunteering time is more useful than giving money.
The important thing is understanding what the contribution is actually supporting. For example, a mosque donation may be connected to a larger community project rather than being simply a one-time payment towards a building. The same idea applies to donations supporting schools, food programmes, shelters, healthcare projects and other community facilities.
Knowing the purpose makes the decision much easier. It also gives donors something concrete to look back on later. Instead of wondering where the money went, there is a clear project or purpose attached to it.
Do Not Automatically Ignore Smaller Organisations
Big charities are easier to find. They have larger websites, more social media activity and usually bigger fundraising campaigns. But bigger does not always mean better. A smaller organisation may be working with one neighbourhood or a particular group of people and understand those needs much more closely.
The downside is that smaller groups may not have the same resources for marketing, reporting or maintaining a polished website. That alone should not make them suspicious. Ask a few basic questions instead. Who runs the project? What will the money pay for? Is there a way to see progress? Are updates provided? If those questions get clear answers, that tells you much more than how professional the website looks.
Keep Giving Realistic
There is also no point setting a charitable giving target that makes everyday finances difficult. Work out what can comfortably be given after rent, bills, food, savings and other commitments are covered. From there, decide whether a regular contribution or occasional donations work better.
It can also help to divide giving between different causes if there is more than one area worth supporting. Most importantly, do not make every donation decision based purely on emotion. Emotion can make a cause feel urgent. Research helps make sure the money actually goes somewhere useful. A few minutes spent checking an organisation, understanding its work and looking at how donations are handled can make a fairly simple decision much more responsible.
You May Also Read : What Is Incestflox? Understanding the Online Search Term and Internet Safety
Managing money sounds simple enough. Spend less than you earn, save what is left and try not to get into unnecessary debt. In reality, it rarely works that neatly. Rent changes. Grocery bills go up. A car needs repairing at exactly the wrong time. An annual payment suddenly appears that was completely forgotten about. Even a few small expenses can start adding up without being noticed. That is why a useful financial plan needs to be practical, not perfect.
Start with Where the Money Actually Goes
The first step is fairly basic, but it is also the part most often skipped: look at the real numbers. Start with monthly income and then list the regular costs. Housing, electricity, transport, groceries, insurance, loan repayments and other essentials should be easy enough to identify.
The harder part is everything else. Coffee runs, takeaway meals, online subscriptions, shopping and small purchases can easily disappear into the background. None of these expenses necessarily needs to be cut out. The point is simply to know how much they are actually costing. It is much easier to make sensible decisions when the numbers are visible.
Don’t Treat Every Expense the Same
A budget does not have to mean saying no to everything enjoyable. Some expenses are necessary. Others are flexible. If money becomes tighter one month, there is a big difference between reducing restaurant visits and being unable to pay the electricity bill. Keeping these categories separate makes difficult months easier to manage.
It can also help to review subscriptions and recurring payments every few months. A service that was useful six months ago might now be barely used. Ten or fifteen pounds here and there may not seem important, but several unnecessary payments can become a decent amount over a year. Sometimes the easiest saving is simply stopping money from leaving the account for things that are no longer needed.
Leave Some Money for Things That Go Wrong
Unexpected costs are not really unexpected. Something will eventually need replacing, repairing or paying for earlier than planned. An emergency fund is there for exactly this reason. It could be a broken washing machine, an urgent trip, a car problem or a temporary drop in income. Without some savings available, even a relatively ordinary problem can mean reaching for a credit card or taking out another loan.
There is no need to build a huge emergency fund overnight. Starting with a realistic amount each month is more useful than setting a target that is impossible to maintain. Over time, even modest contributions can create a useful buffer.
Remember the Expenses That Don’t Come Every Month
Monthly budgets often look fine because they only include monthly bills. Then the annual expenses arrive. Insurance renewals, car costs, school expenses, holidays, memberships and larger household purchases can all create pressure when they have not been considered beforehand. One simple way around this is to take an annual cost and spread it across the year.
For example, if something is likely to cost £1,200 annually, putting aside around £100 each month makes the eventual payment much less painful. The same thinking can apply to charitable commitments and other financial responsibilities. For Muslim households, this may include setting money aside for zakat as part of wider annual financial planning. It does not have to sit in a completely separate financial system. It can simply be included when working out what money needs to be available during the year.
Look at Debt Honestly
Debt can make a financial plan look better on paper than it really is. If a large part of monthly income is already committed to repayments, there is less room for saving, emergencies or future plans.
Start by listing the debts, interest rates and minimum payments. This gives a much clearer idea of what is actually being paid over time. High-interest borrowing deserves particular attention. Paying it down can sometimes have a greater financial benefit than putting extra money into lower-priority goals. And taking on new debt to pay for everyday spending should be treated carefully. It may solve the immediate problem, but the repayment still has to come from a future month’s income.
Give Savings a Specific Job
“Save more money” is a reasonable goal, but it is not a very useful plan. It helps to know what the money is actually for. An emergency fund will have a different purpose from a house deposit. Retirement savings are different again. So are education costs, travel or replacing a car.
Separate goals make it easier to decide how much needs to be saved and how quickly. They also make progress more obvious. Watching a specific savings target move from £500 to £1,000 feels very different from simply seeing money sitting in an account with no particular purpose.
Check the Plan Every Few Months
There is no point creating a detailed budget and never looking at it again. Financial circumstances change. Income changes. Bills change. Household priorities change too. A quick review every few months can be enough to catch problems early. Look at actual spending, check whether savings are still realistic, review debt and think about any larger expenses coming up. The goal is not to track every single purchase forever. It is to have a reasonable idea of where the money is going and whether it is still supporting the things that matter.
Good financial planning is really about creating some breathing room. It makes everyday spending easier to understand, gives future goals a better chance and reduces the chance that one unexpected bill completely throws everything off. It will never make money management completely predictable. Nothing can do that. But a decent plan can make the unpredictable much easier to handle.
You May Also Read : Phoenix Home Care: Essential AC, Plumbing, and Maintenance Tips
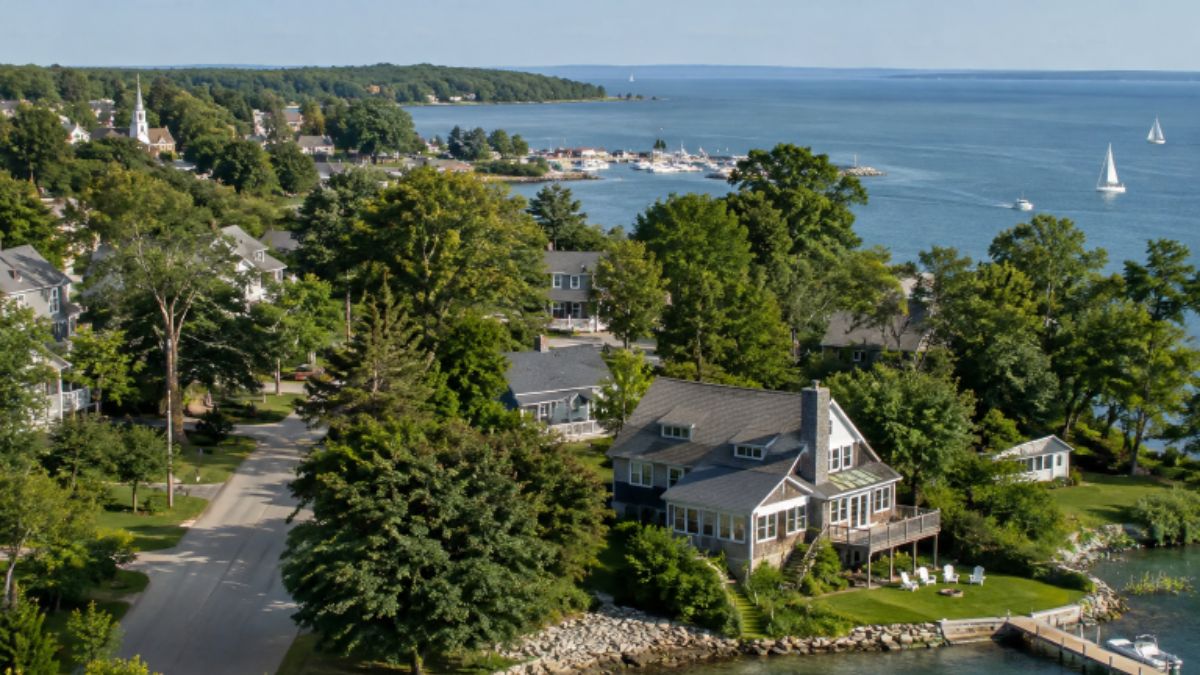
Buying a vacation home in Ephraim, Wisconsin can mean having a place for long weekends, family gatherings, time on the water, and a future change of pace. It is also a substantial purchase with responsibilities that may look very different from those of a primary residence.
Start by comparing property styles, locations, and current asking prices through Ephraim Homes for Sale. Arbor Crowne Properties is an Ephraim-based brokerage with a local home-search resource covering available homes in and around the village, including cottages, condominiums, wooded properties, and waterfront-oriented options. Its local focus can help buyers evaluate choices in Ephraim and nearby Door County communities with a clearer view of the area.
Define the Purpose of the Property
A clear purpose makes every later decision easier. A summer cottage for occasional weekends may need simple storage, outdoor living space, and low-maintenance systems. A future retirement home may need reliable year-round access, bedroom flexibility, and practical heating. Buyers considering rentals may place greater value on parking, bedroom count, guest appeal, and straightforward arrival logistics.
Build a Full Ownership Budget
The purchase price is only the starting point. Include the down payment, closing costs, property taxes, insurance, utilities, furnishings, lawn care, snow removal, and routine repairs. Older cottages and properties with private wells, septic systems, docks, decks, retaining walls, or private-road obligations deserve an additional reserve fund. Ask for recent utility and maintenance information when available, then budget conservatively for replacements that cannot be precisely predicted.
Compare Property Types in Ephraim
Detached Cottages
Cottages can offer privacy, character, and dedicated outdoor space. They can also place all exterior and mechanical maintenance on the owner, so inspect roofs, foundations, drainage, heating, and winterization plans closely.
Condos
Condominiums may simplify some exterior responsibilities, but association dues and rules matter. Review the declaration, budget, reserves, rental policy, pet rules, parking limits, and any restrictions on renovations before making an offer.
Waterfront and Inland Homes
Waterfront homes may offer views and direct access, while inland or wooded properties may provide privacy and more separation from busy areas. Either choice requires practical checks for drainage, driveway access, internet availability, tree maintenance, and seasonal conditions.
Check the Location in Every Season
A July showing cannot reveal everything about a Door County property. Drive the route from home to major roads, grocery stores, medical services, and everyday necessities. Note weekend traffic, nearby activity, cellular coverage, and road conditions. For a better sense of nearby recreation, services, and community options, the Door County visitor centers can help buyers orient themselves before spending more time in Ephraim and surrounding villages.
Review Waterfront Rules Before Making Plans
Do not assume a waterfront purchase automatically allows a new pier, shoreline work, tree removal, an addition, or a larger deck. Shoreland zoning, permits, setbacks, erosion concerns, wells, septic systems, and flood-related considerations can affect both present use and future projects. Wisconsin buyers can review water-related property considerations before committing to a home near water.
- Confirm which zoning and shoreland rules apply to the parcel.
- Ask about existing docks, access structures, and permits.
- Identify the well, septic system, drainage paths, and, when applicable, the ordinary high-water mark.
- Discuss whether planned additions or shoreline changes may require approval.
Study the Home’s Condition
A polished interior does not replace a thorough inspection. Focus on the roof, chimney, foundation, electrical panel, plumbing, heating, attic ventilation, windows, siding, decks, and signs of moisture. Depending on the property, a general inspection may need support from specialists for wells, water quality, septic systems, radon, structural concerns, chimneys, or shoreline conditions.
Check Rental and Association Rules
Rental income should remain a possibility, not a budget assumption, until all applicable rules have been confirmed. Ask the municipality about licensing or registration requirements, verify the zoning classification, and read association documents in full. Also consider occupancy limits, parking, noise standards, cleaning costs, insurance, management fees, and realistic vacancy periods.
Compare the Property With Recent Sales
Useful comparisons share more than a nearby address. Evaluate water access, views, lot size, condition, bedroom count, updates, included furnishings, road arrangements, and restrictions. A home with a better shoreline, newer systems, or fewer limitations may not be a true match for the property you are considering. Local comparable sales and active listings should inform, rather than replace, an inspection and careful due diligence.
Ask Better Questions During a Showing
- How long is the home typically used each year?
- Which repairs and upgrades were completed recently?
- How old are the roof, furnace, water heater, and major appliances?
- Who handles winterization, snow removal, and seasonal opening?
- Are there shared driveways, private roads, easements, or access agreements?
- Have there been water issues, insurance claims, or septic concerns?
- Which furnishings, equipment, and outdoor items are included?
Make the Offer With Future Use in Mind
Offer terms should reflect the home’s condition, financing, comparable sales, and your intended use. Inspection, financing, appraisal, title, survey, well, septic, association documents, and rental rule contingencies can provide important time to evaluate a purchase. Waiving protections should be a deliberate decision made with a clear understanding of the potential risk.
Common Questions About Buying a Vacation Home in Ephraim
Is Ephraim a good place for a second home?
Ephraim may suit buyers who value a small-village setting, access to Door County recreation, historic character, and proximity to other communities on the peninsula. Whether it is the right fit depends on how often you will visit, your preferred level of activity, and your maintenance expectations.
Are waterfront homes more difficult to maintain?
They may require additional planning due to moisture exposure, shoreline conditions, weather, insurance considerations, and regulations governing improvements near the water.
Should buyers consider a condo?
A condo can be a practical choice for owners who prefer shared exterior maintenance, but dues, reserves, rules, and rental restrictions deserve the same careful review as the unit itself.
Buy for the Life the Property Can Support
The best Ephraim vacation home is not simply the one with the most appealing view. It is the property that fits your budget, schedule, comfort with maintenance, family needs, and long-term plans. Careful attention to location, condition, regulations, and future costs can make ownership more enjoyable and far less surprising.
-
 Business6 months ago
Image Search Techniques: Smarter Ways to Find Accurate Visual Results Online
-
Health5 months ago
Why Are So Many Autistic Girls and Women Still Missing Out on Early Identification?
-
 Lifestyle8 months ago
Sustainable Ways to Buy and Sell Antiques
-
 Sports5 months ago
Ultimate Pragmatic Juara100.org Medal Achievement Guide for Maximum Rewards
-
 Education5 months ago
How You Structure Dissertation Research to Build Strong Academic Arguments
-
 Topic1 month ago
Guide to Choosing Asphalt Maintenance for San Diego, CA Properties
-
 Technology6 months ago
TabooTube: What It Is, How It Works, and Whether It’s Worth Your Time
-
 Technology8 months ago
Top Features of ProgramGeeks Social You Didn’t Know About